Review R&D disallowances
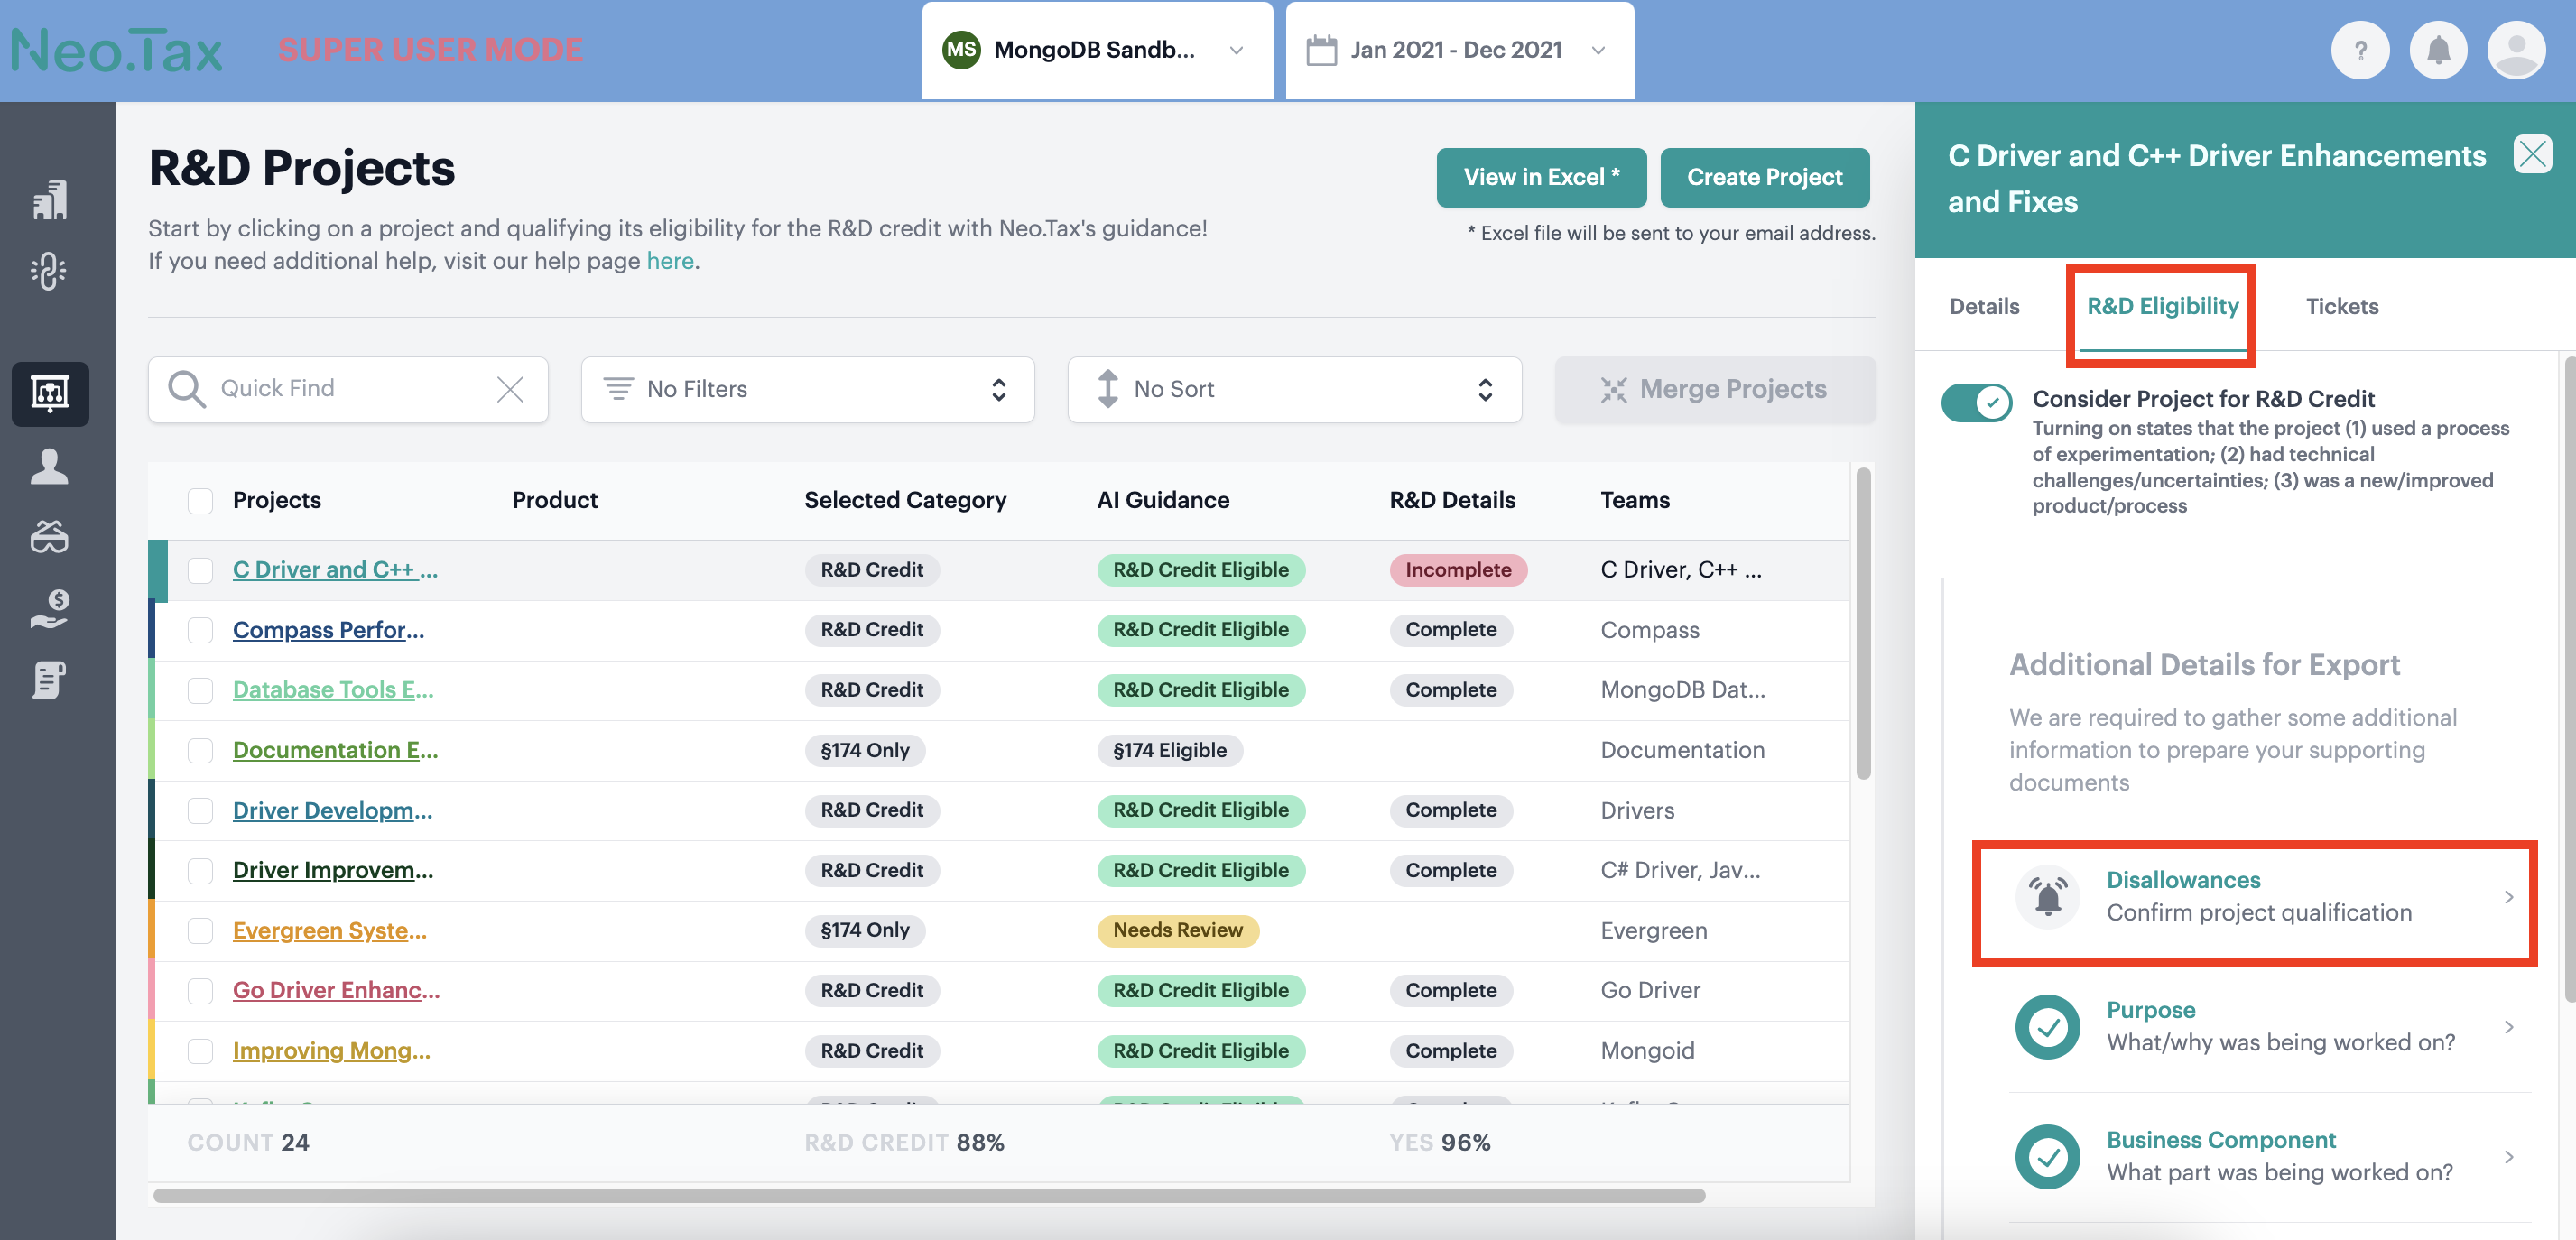
Activities that involve any of the items in the list below do not qualify for the R&D tax credit. This information is confirmed within the R&D Eligibility menu for each project on the R&D Projects page in Neo.Tax (see screenshot below).
Activities that are not qualified for the R&D tax credit:
-
Testing/QA for project in production: Activities conducted after the beginning of commercial production do not qualify for the R&D tax credit. Activities are conducted after the beginning of commercial production if such activities are conducted after the component is developed to the point where it is ready for commercial sale or use, or meets the basic functional and economic requirements of the taxpayer for the component’s sale or use.
-
Surveys/market research: Activities related to the items below do not qualify for the R&D tax credit:
- Efficiency surveys;
- Management functions or techniques, including such items as preparation of financial data and analysis, development of employee training programs and management organization plans, and management-based changes in production processes (such as rearranging work stations on an assembly line);
- Market research, testing, or development (including advertising or promotions);
- Routine data collections; or
- Routine or ordinary testing or inspections for quality control.
-
Research outside US/PR/US territories: Research conducted outside the United States, the Commonwealth of Puerto Rico, and other possessions of the United States do not qualify for the R&D tax credit.
-
Reverse engineering an existing product: Activities related to reproducing an existing business component (in whole or in part) from a physical examination of the business component itself or from plans, blueprints, detailed specifications, or publicly available information about the business component are not qualified for the R&D tax credit.
-
Research funded by grant, contract, other entity: Qualified research activities funded by any grant, contract, or otherwise by another person (or governmental entity) are not qualified for the R&D tax credit.
-
Social science research: Qualified research activities that include research in the social sciences (including economics, business management, and behavioral sciences), arts, or humanities, are not qualified for the R&D tax credit.
-
Adaptations for a specific customer: Activities related to adapting an existing business component to a particular customer’s requirement or need do not qualify for the R&D tax credit.
-
Internal-use software for back-office function: Activities related to software that is developed primarily for general and administrative functions, including financial management, human resources, and/or support services (i.e., data processing, graphic services, marketing, legal services, government compliance services, printing and publication services, and security services), is rarely eligible for the R&D tax credit.